

ReelMoney: Watch & Earn Cash analysis by Appwee
I approached ReelMoney as a small finance app with a simple promise: spend a little time watching short videos and completing tasks, then turn the points you collect into rewards. That idea is easy to understand, but the real question is whether the experience feels worthwhile after the novelty wears off. My overall view is cautiously positive. It is free, easy to try, and more approachable than many traditional money-management tools, yet it should be treated as a casual rewards activity rather than a dependable way to earn income.
The app is developed by Debug Entity Dev and sits in the finance category, although it feels quite different from banking, budgeting, or investing software. Its focus is small, repeatable actions rather than managing an account balance or planning long-term goals. That distinction matters. If you are looking for a place to track spending, move money, or build a budget, this is the wrong kind of finance app. If you want a lightweight way to fill spare minutes while collecting points, it makes more sense.
How ReelMoney feels in everyday use
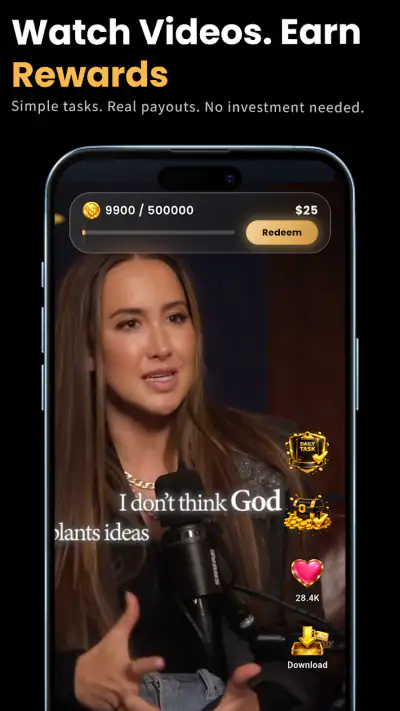
The first thing I noticed is how quickly the concept becomes familiar. You open the app, look for an available video or task, complete it, and return to the rewards flow. There is no complicated financial setup to learn before you can understand what you are doing. The short-video format makes the app feel closer to a rewards lounge than a conventional finance tool, which may appeal to people who dislike dense dashboards and long forms.
The strongest part of the experience is its low barrier to entry. The app is free, carries an Everyone age rating, and works on devices running Android 7.0 or later. That broad compatibility gives it a practical advantage for people using older phones. I also like that the core activity is divided into small pieces. You do not need to reserve a large block of time; a spare moment can be enough to check what is available and decide whether a task is worth doing.
That convenience should not be confused with speed. The app’s model depends on accumulating points through repeated activity, so the value of any single video or task is likely to feel modest in isolation. I found it more useful to think in terms of a routine than a single session. Opening it briefly when I would otherwise scroll aimlessly makes more sense than expecting a meaningful reward after only a few minutes.
A realistic use case would be waiting for a bus, sitting in a reception area, or taking a short break between errands. In that situation, ReelMoney can give idle screen time a small purpose. I would not use it during a focused work period, and I would not replace a paid task or part-time opportunity with it. The app works best when the time is already available and the user is comfortable stopping whenever the activity no longer feels worthwhile.
One useful habit is to decide in advance how much attention you are willing to give it. For example, I would check the available tasks once, complete only the ones that look clear and reasonable, and then leave rather than repeatedly refreshing. This prevents a common trap with reward apps: spending more time hunting for opportunities than the eventual points justify. The app becomes easier to judge when you measure it against your spare time, not against a full wage.
The reward loop is easy to understand, but expectations matter
ReelMoney’s central loop is built around points and redemption. That is more accessible than apps that require users to understand investment risk, payment schedules, or financial terminology. A first-time user can grasp the basic purpose almost immediately. The trade-off is that the experience has less depth than a genuine personal-finance application. It does not replace a budget planner, a savings tracker, or a banking app because its job is different.
I would also approach the word “cash” carefully. In everyday conversation, users may read it as a promise of regular earnings. In practice, rewards apps are better understood as a way to collect small benefits through engagement. The sensible approach is to explore the redemption area early, understand the available choices, and avoid treating unredeemed points as money you already possess. That mindset keeps the experience practical and reduces disappointment.
Another worthwhile workflow is to separate discovery from completion. I would first scan the task list and note which activities are understandable, short, and relevant to my interests. Only then would I begin completing them. This avoids spending time on a task whose instructions are unclear or whose reward does not seem appropriate for the effort. It is a small change, but it makes the app feel more deliberate and less like endless tapping.
The app has attracted a substantial audience, with over one hundred thousand installs and an average rating of 4.8 from around fourteen thousand ratings. Those figures suggest that many people find the basic experience satisfying, but they do not guarantee that every user will value the same things. A high rating can reflect ease of use, entertainment, or successful reward collection; it should not be read as proof that the app produces significant income.
There is also a useful distinction between ratings and written feedback. Around two and a half thousand reviews give the overall score more context than a handful of comments would, but I would still read recent user experiences before committing much time. Reward services can feel different as task availability changes, and personal expectations vary widely. Someone seeking a little extra activity may be delighted, while someone calculating an hourly return may reach a very different conclusion.
Where the app is genuinely convenient
The clearest strength is the combination of simple actions and a familiar mobile format. Many people already understand short videos, so the learning curve is gentler than it would be for a specialized financial product. Tasks add another route for engagement, which is helpful when watching videos alone becomes repetitive. I appreciate that the app does not require me to become a finance enthusiast before I can use it.
It is also a reasonable option for users who want to keep their main financial life separate from their reward activity. A budgeting app asks me to record expenses and make decisions about money I already have. ReelMoney asks me to participate in a points system. Those are fundamentally different jobs, and keeping that difference clear helps prevent poor financial decisions.
For older Android devices, the minimum operating-system requirement is another practical point in its favor. People who cannot or do not want to upgrade to a recent phone may still be able to try it. Compatibility alone does not make an app good, but it removes one common obstacle for casual users.
The age rating of Everyone also makes the presentation broadly approachable. I would still encourage families to discuss how reward apps work, especially with younger users. The important lesson is that points are earned through activity and should not be confused with guaranteed income. That conversation is more valuable than simply assuming an age label explains the entire experience.
The main weakness is the value of time
The biggest limitation is not the basic idea; it is the uncertainty around whether each session feels worth the time. Watching a short video is easy, but repeating that action can become monotonous. Tasks may make the loop more varied, yet repetition remains part of the model. If you are highly conscious of your time, you may quickly decide that entertainment or learning offers a better return.
This is where ReelMoney differs from the usual alternatives in finance. A budgeting app can help identify unnecessary spending, and that saving can have a meaningful long-term effect. A bank rewards program may connect benefits to purchases you were already planning to make. A freelance platform can offer larger payments, but it demands real work and usually more commitment. ReelMoney occupies a lighter space: less effort than paid work, but also less dependable value.
I would not recommend using it with the expectation of covering bills, building an emergency fund, or replacing employment. That would put too much weight on a casual points system. It is better suited to optional screen time, where any reward is a bonus rather than part of a financial plan. If your priority is improving your finances, a spending tracker or savings method will probably have a more lasting impact.
Another point to watch is attention management. Because the activities are short, it is easy to keep going simply because the next task appears manageable. I found that setting a stopping rule is more useful than chasing an abstract total. Stop after a fixed amount of time, after completing a small group of tasks, or when the available options no longer seem worthwhile. This keeps the app from quietly taking over the break it was supposed to fill.
Redemption is also the moment when expectations become concrete. Before investing serious time, I would inspect how the app presents its reward choices and make sure I understand the steps involved. A points balance can look encouraging, but the practical value depends on what those points can ultimately be exchanged for and how straightforward the process feels. The safest approach is to regard the redemption path as part of the product, not as an afterthought.
Because the current version is 1.0.0, I would give the app some room to mature while also keeping expectations measured. Early versions can provide a clean starting point, but they may also feel less established than long-running alternatives. This does not make ReelMoney unusable; it simply makes it sensible to judge the actual day-to-day experience rather than assuming that a promising concept will automatically suit everyone.
Who should try it, and who should skip it
I think ReelMoney is a good fit for someone who enjoys short, low-pressure activities and wants to turn occasional idle time into points. It may suit users who prefer a straightforward interface over a complex financial dashboard, people with compatible older Android phones, and anyone who is comfortable viewing rewards as a small extra rather than a source of income.
It can also work for a person who likes testing new apps without paying an entry fee. Since it is free, there is little financial risk in trying it briefly. My advice would be to use a short trial period, learn how the video and task routines feel, and then decide whether the rewards justify continuing. That is more reliable than judging the app from its concept alone.
I would skip it if you dislike advertising-style content, repetitive actions, or reward systems that require patience. I would also choose a different tool if my goal were budgeting, credit management, investment research, bill organization, or serious income generation. ReelMoney is not a universal finance solution, and forcing it into one of those roles would lead to the wrong expectations.
For parents or guardians considering it for a younger user, I would frame it as an activity app with a points component, not as a lesson in earning money. Discussing screen time and the difference between points and spendable funds is important. The Everyone rating makes the app broadly accessible, but responsible use still depends on how the user understands the reward loop.
My verdict after weighing the trade-offs
My final opinion is that ReelMoney is worth a cautious try for the right kind of user. Its strongest qualities are accessibility, a clear points-based routine, free entry, and compatibility with older Android versions. The combination of short videos and tasks gives idle moments a simple structure, and the app is easy to understand without financial expertise.
Its weakness is equally clear: the value depends on how much time you are willing to spend for rewards that should be viewed modestly. The activity can become repetitive, and it is not a substitute for work, saving, or proper money management. I would keep it as an optional side activity, set limits before using it, and examine the redemption process early rather than assuming that every collected point will feel equally valuable.
Debug Entity Dev has created an approachable finance app with a narrower purpose than the category label might suggest. If you want a casual way to use spare minutes and you enjoy points-based incentives, it may fit comfortably into your routine. If you want measurable financial progress, choose a budgeting or savings tool instead. The best reason to install it is convenience, not the promise of dependable income.
Gallery
ReelMoney: Watch & Earn Cash Pros and Cons
- Simple interface makes videos easy to browse and watch.
- Offers several ways to earn
- including videos
- tasks
- and referrals.
- Low-effort activities can be completed in short spare-time sessions.
- Reward progress is visible
- helping users track points and cash-out goals.
- New users can usually start earning without paying an upfront fee.
- Earnings per activity may be small and require considerable time.
- Cash-out thresholds can make rewards feel slow to reach.
- Available tasks and payout options may vary by country.
- The app may show frequent ads while you complete earning activities.
- Referral-based bonuses may limit earning potential without inviting others.
ReelMoney: Watch & Earn Cash Frequently Asked Questions
What is ReelMoney: Watch & Earn Cash, and how does it work?
ReelMoney: Watch & Earn Cash is a rewards app centered on short videos and other in-app activities. After creating an account, users can browse available content, collect points or virtual rewards, and potentially exchange their balance for supported cash-out options. The exact earning methods, reward values, and redemption requirements may vary by location and can change over time.
Can you really make money with ReelMoney, and how much can users earn?
ReelMoney may provide small rewards for watching videos and completing eligible tasks, but it should not be considered a reliable income source. Earnings are generally modest and depend on the number of available offers, your region, activity level, and the app’s current reward rates. Users should treat it as casual entertainment with occasional rewards rather than a way to earn substantial money.
What are the withdrawal requirements and available payment methods?
Before spending significant time in the app, check the current minimum withdrawal threshold, verification rules, processing time, and payment methods shown in your account. Reward platforms commonly require users to reach a specific balance and may request accurate account details before processing a payout. Options and availability can differ between countries, so the withdrawal page is the most reliable source.
Is ReelMoney: Watch & Earn Cash safe to use?
The app should be downloaded only from an official Google Play or Apple App Store listing, and users should review its permissions, privacy policy, developer information, and recent ratings before registering. Avoid sharing unnecessary sensitive information, never pay money to unlock a withdrawal, and be cautious of suspicious links or requests for account credentials. As with any rewards app, privacy and payout experiences can vary.
What should I know before downloading ReelMoney?
ReelMoney may be suitable for people who enjoy short videos and want to collect occasional rewards, but users should read the terms carefully before joining. Confirm whether the app is available in your country, understand how points are earned and converted, check whether advertisements are frequent, and review the latest user feedback. Reward rules, supported devices, and redemption conditions may change after installation.














